The alternatives to manual claims review are more reviewers, in-house or through an outsourced desk review firm; rules and extraction tools that pull fields out of the documents; and an intelligence layer that reads the whole file and hands your adjusters findings with the evidence attached. The first adds hours. The second adds data. The third adds the reading itself. In all three, the decision stays with your people.
What manual review misses under pressure
Nobody can read 300 pages under pressure. Everybody has to.
A property claim is a stack of documents nobody has time to read, and a policy that changes the answer on page 34. Your best people cope on experience and trust, and most days that works. But the gap between what was written and what was read quietly becomes money. The busier the week, the wider the gap.
That gap shows up in four places:
- Leakage. Coverage gaps get missed and numbers stop reconciling. Money goes out the door that should not, and it does not come back. That is claims leakage.
- Speed. Claims sit and families wait. A slow claim becomes a complaint, a complaint becomes a dispute, and a dispute becomes a lawyer. Reading the file before anyone opens it is how you reduce claims cycle time.
- Experience. The moment a family needs their insurer most is the moment the process is slowest. That is when loyalty is decided.
- Capability. The adjusters who knew everything are retiring, and the next generation is learning on live claims, with real money at stake. That is a question of adjuster training and capacity.
The fortieth file on a Friday gets less attention than the first one on Monday. Not from carelessness. From arithmetic.
Three alternatives
1. More people: hire, or send files to outsourced desk review
Adding reviewers is the oldest answer, and it works when the extra volume is predictable. A good desk reviewer brings experience and a second pair of eyes. The catch is that capacity grows one person at a time, while a storm can multiply the queue in a week. Outside reviewers also have to learn your forms, and the reading is still done by hand, at the same speed, under the same pressure.
2. Rules and extraction tools
Extraction tools pull fields out of documents: the claim number, the loss date, the estimate total, the line items. Rules then flag claims above a threshold or route them by peril. This is useful work. It feeds your core system clean data and gets claims to the right desk. Where it stops is meaning. Extracting a field is not reading a clause, and an endorsement that changes what another provision means is not a field. Someone still has to read the policy.
3. An intelligence layer that reads the whole file
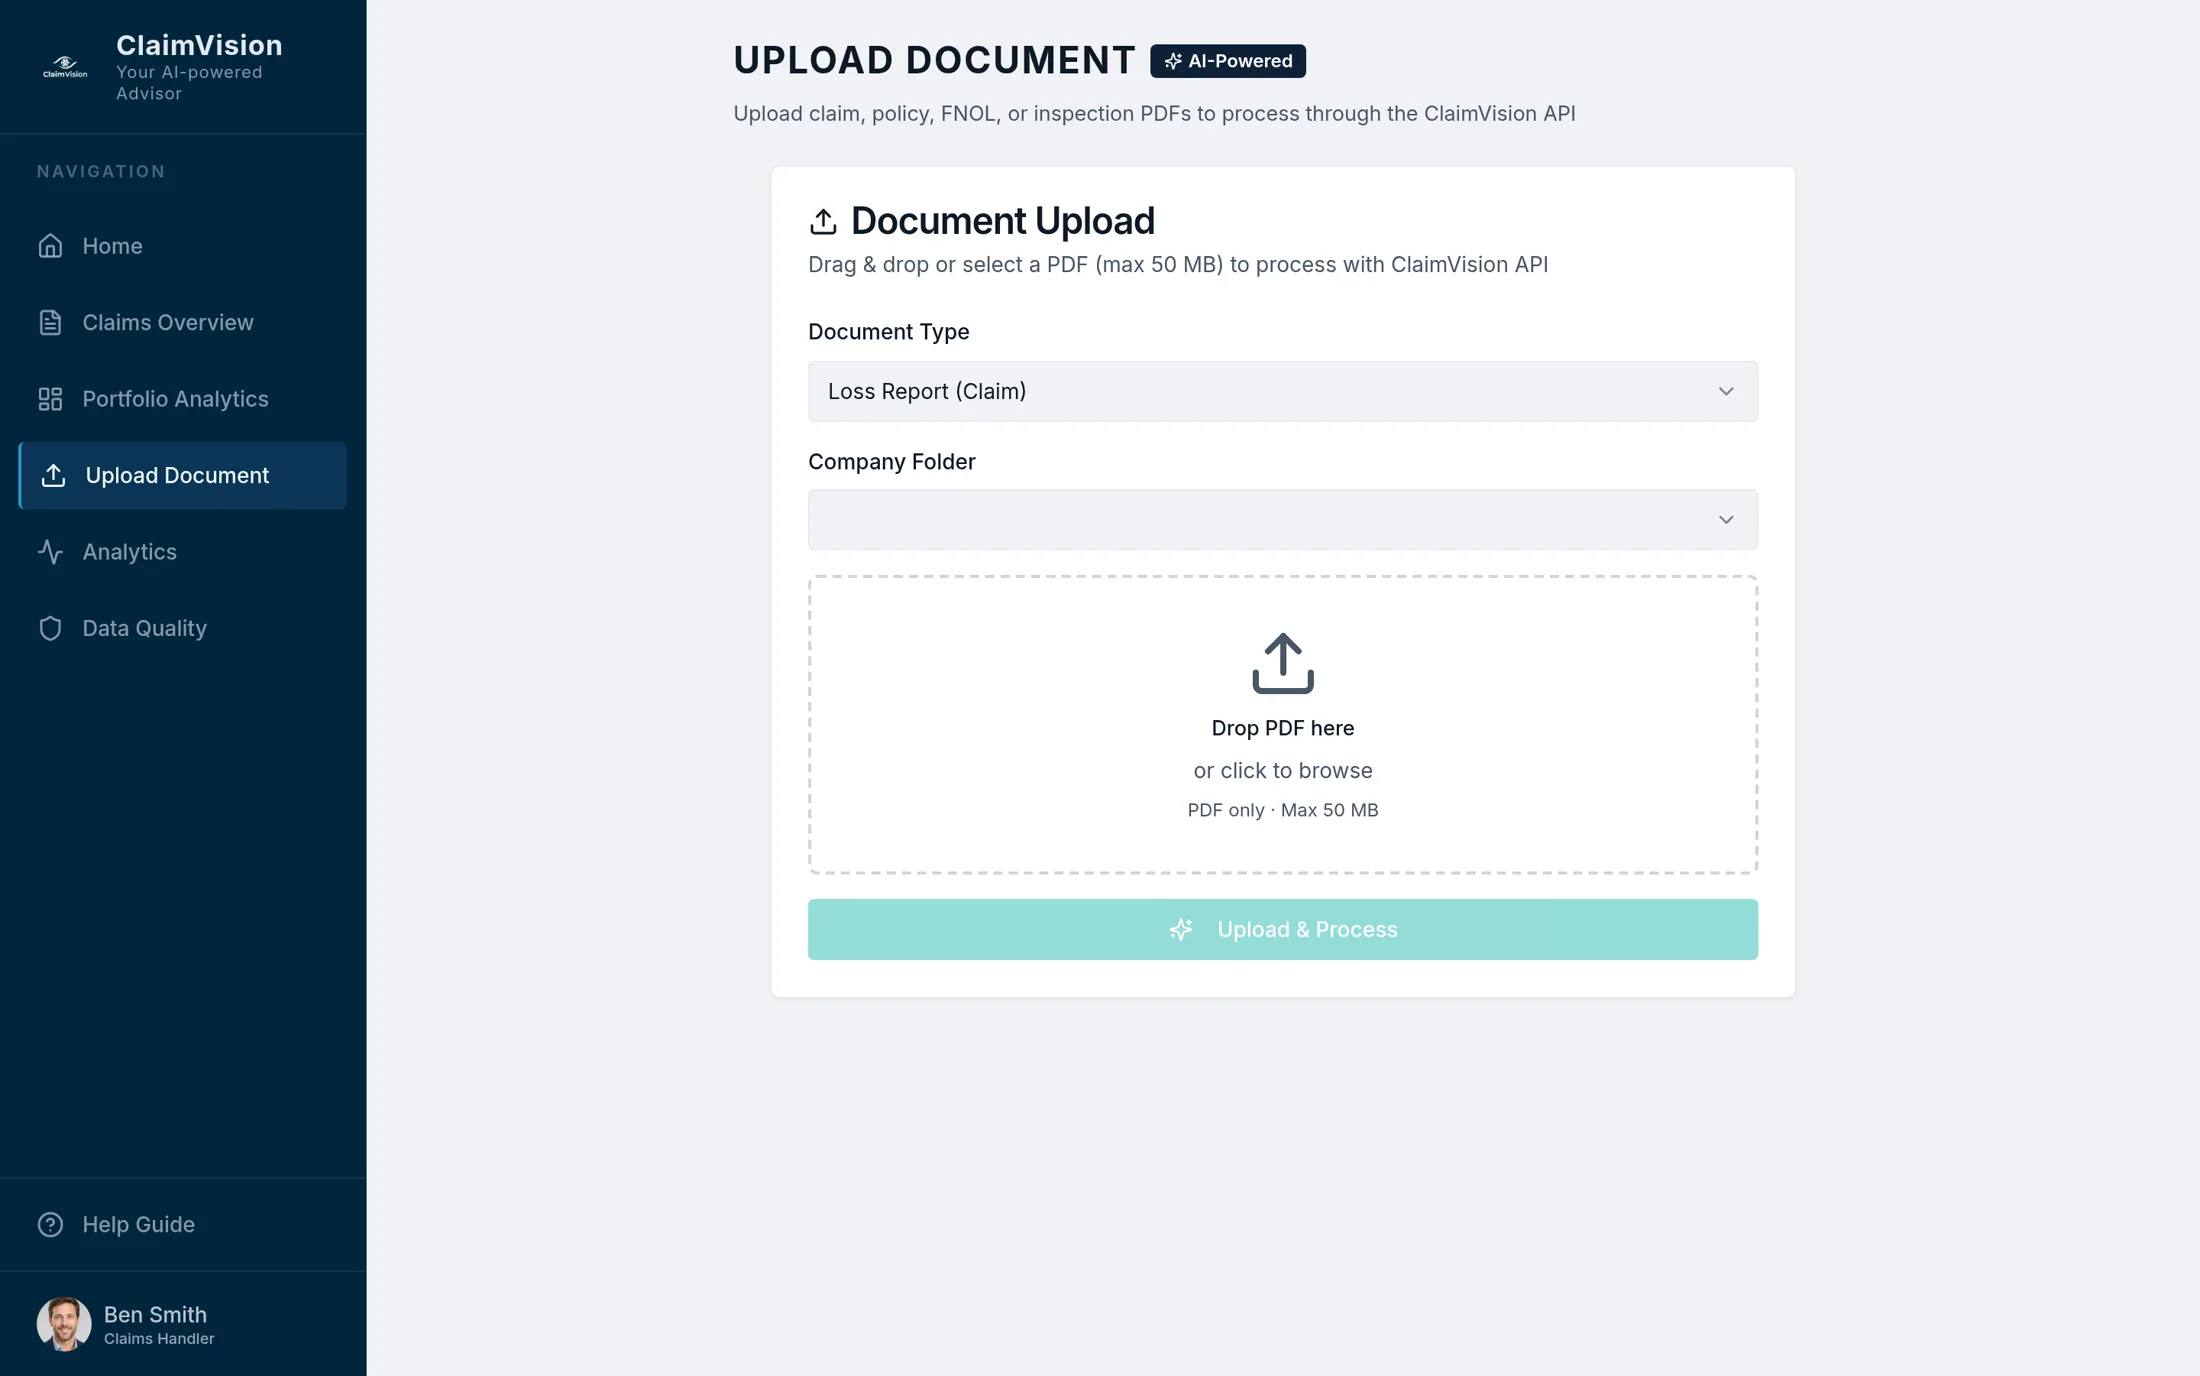
The third alternative reads the report, the estimate, the policy and its endorsements, and the photos together, before the adjuster opens the file. It hands back a one-page view, findings with the clause and the dollar impact attached, and figures that reconcile. The benchmark we publish: a full day's reconciliation work on a real large-loss claim, done exactly, in under a minute. The catch is trust. It has to earn its place beside people who have done this for years, one claim at a time. This is what AI claims intelligence means, and it is how AI property claims review works in ClaimVision.
The three alternatives, compared
| More reviewers | Rules and extraction | Intelligence layer | |
|---|---|---|---|
| What it adds | Hours | Structured data | The reading |
| Reads policy and endorsements together | By hand, as time allows | No, it pulls fields | Yes, on every claim |
| The week a storm lands | Capacity grows one hire at a time | Keeps routing at volume | Every file gets the same careful read |
| What the adjuster receives | A colleague's notes | Fields in the core system | Findings with the clause and dollar impact |
| Where it falls short | Cost and speed scale with headcount | A clause is not a field | Has to earn trust, claim by claim |
| Who decides | Your adjuster | Your adjuster | Your adjuster |
Five questions to ask a vendor
- Will you run it on closed claims we already know the answer to, before it touches a live one?
- When it finds something, does it show the page, the clause and what it is worth on this claim?
- When the policy language reads two ways, does it decide silently, or put the call in front of a person?
- Is every recommendation and every human override kept, so we can show a regulator an AI claims audit trail?
- Do we have to change our core system? The answer should be no. You do not need to replace Guidewire ClaimCenter or Duck Creek to add an AI layer on a core claims system.
The first question matters most. A closed file you already know the answer to is the fairest test there is. For the longer argument on reading the file where it already lives, see our guide to unstructured claims documents.
Whichever route you take, the reading can go to the machine. The judgement stays with your people.
Bring a closed claim you already know the answer to. Thirty minutes is enough.
Book a demo